
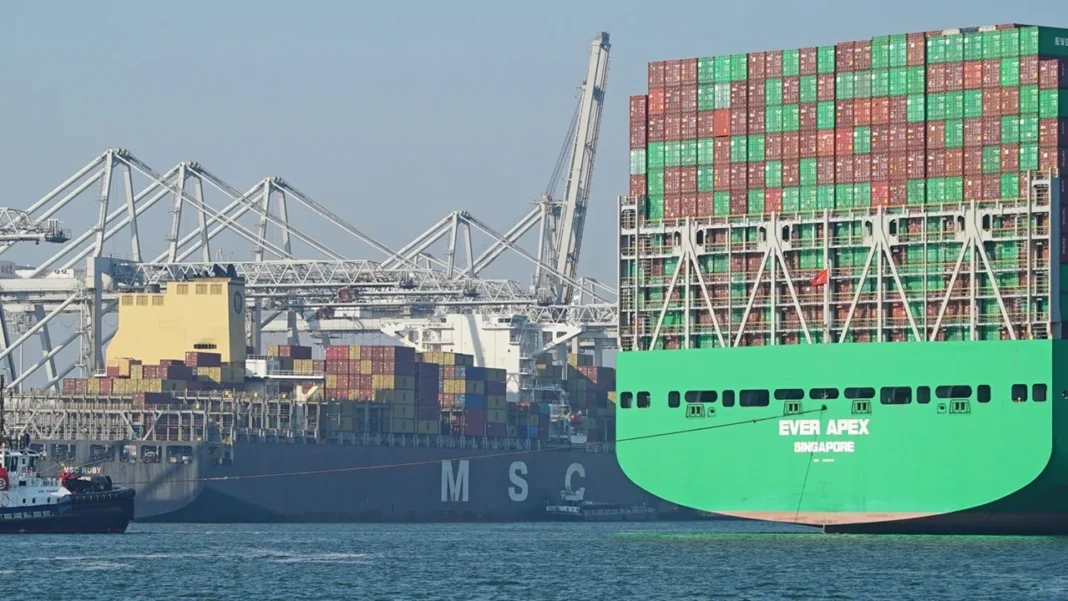


reight rates out of Asia to Europe and the US began to climb after the US attacked Iran, but while Pacific charges have continued to climb, European freight has stalled.
Drewry data shows Shanghai to Rotterdam rates declined 2% to $3,337/feu and Shanghai to Genoa prices were down just $6 week-on-week, the decline was more than $430/feu in the previous week.
Summer cargo levels have been unprecedented, with Container Trades Statistics stating that “August 2026 delivered yet another record month for global container trade.”
With freight movements reaching 17.46m teu, August surpassed the previous record set a month earlier in July and was 4.7% higher in the first eight months of the year, compared to 2025.
CTS said that the Pacific, up 5% year-on-year, and Sub-Saharan Africa, up 13%, have contributed to the increases, but CTS figures necessarily lag behind the market and in October Asian holidays will play a role.
Clearly, the Golden Week holidays have played a part in the softening of rates, but Drewry added: “Six blank sailings have been announced for next week, up from five this week, indicating a slight reduction in scheduled capacity.”
The consultant said that carriers are attempting to stop the slide by introducing higher FAK rates, from the second half of this month.
Even with the cuts to capacity and the attempts to prevent further rate erosion it remains unclear whether the carriers can make those increases stick.
“The faster-than-expected return to the Suez route remains the biggest threat to carrier efforts to support rates, which have declined for 13 consecutive weeks on the Asia–Europe trade,” said Drewry.
Drewry expects both the Asia to Europe and Pacific trades to remain volatile in the short-term with geopolitical and climate events causing capacity limitations.
Since July, however, spot rates out of Asia “Have fallen heavily,” noted Xeneta’s chief analyst Peter Sand.
“The Mediterranean is taking the biggest hit, down 43% since 1 July, while North Europe is down 34%. The pace of the decline has eased a little, but rates are still elevated and the trend is still downward, so we are not at the floor yet,” warned Sand.
As the European contracting season is now in full swing, carriers’ attempts to arrest the slide on European rates will be more concerning. Shippers, however, may welcome the respite, as the market situation finally swings toward the carrier’s customers, as they benchmark long-term charges against spot rates.
“Demand has been very strong all year, not least into Europe, but it could not keep growing at double digits indefinitely. As demand eases from a very high level, the fight for capacity eases too, and even freight forwarders are now getting better deals from carriers in long-term contract negotiations,” said Sand.
Xeneta data shows Pacific rate growth has stabilised, increasing just 1.1% and 0.5% week-on-week to the US West and East coasts, respectively.
Conversely, European spot rates fell 2.5% to North European destinations, and 5.9% to the Mediterranean.