
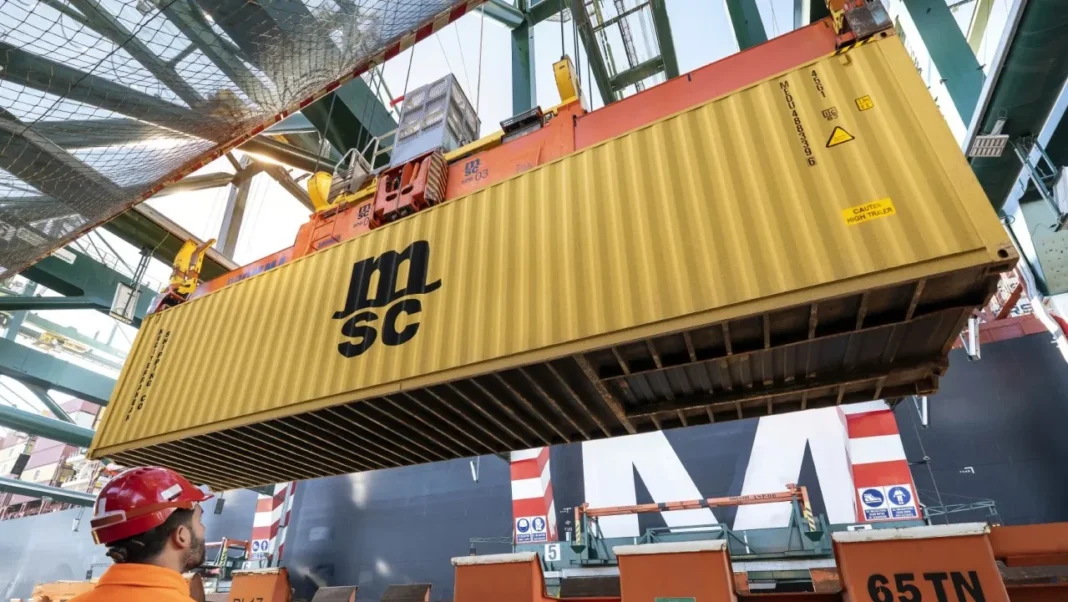


MSC is the lone wolf of container market following the dissolution of the 2M alliance with Maersk last year, but they are not the only carrier shifting towards standalone services.
Antonella Teodoro, consultant with MDS Transmodal, looked at the alliance data on the three major trades, comparing April 2025 statistics with April data from this year, to see how services were being restructured as the Middle East conflict eases.
“Overall, the data suggests that the post-restructuring the liner shipping market is not moving towards greater alliance dominance. Instead, while alliances remain central to network design, carriers are increasingly deploying capacity through a wider range of standalone and cooperative arrangements across the major east–west trades,” commented Teodoro.
Transpacific – alliances versus standalone services
A case in point is the Pacific trade, the most distant from the Middle East conflict, but still affected as the price of oil has raised the cost of bunkers and dampened demand.
Of the three major alliances both Ocean and Gemini maintained stable capacity levels, while Premier Alliance showed the fastest growth in the region, raising its deployment by over 22%.
MSC reduced its capacity by 7.5%, however, “The most significant development was the expansion of the ‘Others’ category, which grew by 13% to exceed 1 million teu/month,” noted Teodoro.
Independent and non-alliance services accounted for roughly 70% of all market growth recorded between April 2025 and April 2026, increasing their share of total capacity from 34% to 36%, she added.